

Editorial note: This article continues our series on the post-AI challenges facing pre-AI companies, and the flip side: what the AI winners actually look like under the hood. If you want to catch up on the series:
2/10/26 - The Tweener Founder Bat Phone is Ringing off the Hook here.
4/30/26 - Competitive Moats in the AI Era (from RDSW) here.
5/9/26 - The Hardest Thing for Early Stage NC Startups - Finding the Elusive ‘Lead’ Investor.
5/25/26 - SaaS Apocalypse: Jes Lipson on how SaaS founders can navigate the chaos.
8/11/26 - SaaS Apocalypse takes a turn for the worse: Airtable + Bending Spoons, Todd Olson @ Pendo chimes in here.
We couldn’t share posts like this without our amazing sponsors:
Featured Platinum Sponsor

Featured Gold Sponsor

Featured Silver Sponsor

The Anthropic S-1 Details and Highlights
On Monday 10/26, Anthropic filed its S-1 to list on the Nasdaq under the ticker ANT. If you have an hour, read the risk factors section. I did (ok, with Claude’s help, 557 pages is a lot) and it is the single best document on the economics of AI that a founder can get their hands on right now.
Highlights:
Anthropic was founded in 2021. Five years old, it is going public at a $1.5-2T valuation, being taken out by the two bluest of blue-chip investment bankers, Goldman Sachs and Morgan Stanley - this will probably be the best venture capital return ever. Spark Capital put in about $777M and that stake would be worth about $10.9B at $1.5T.
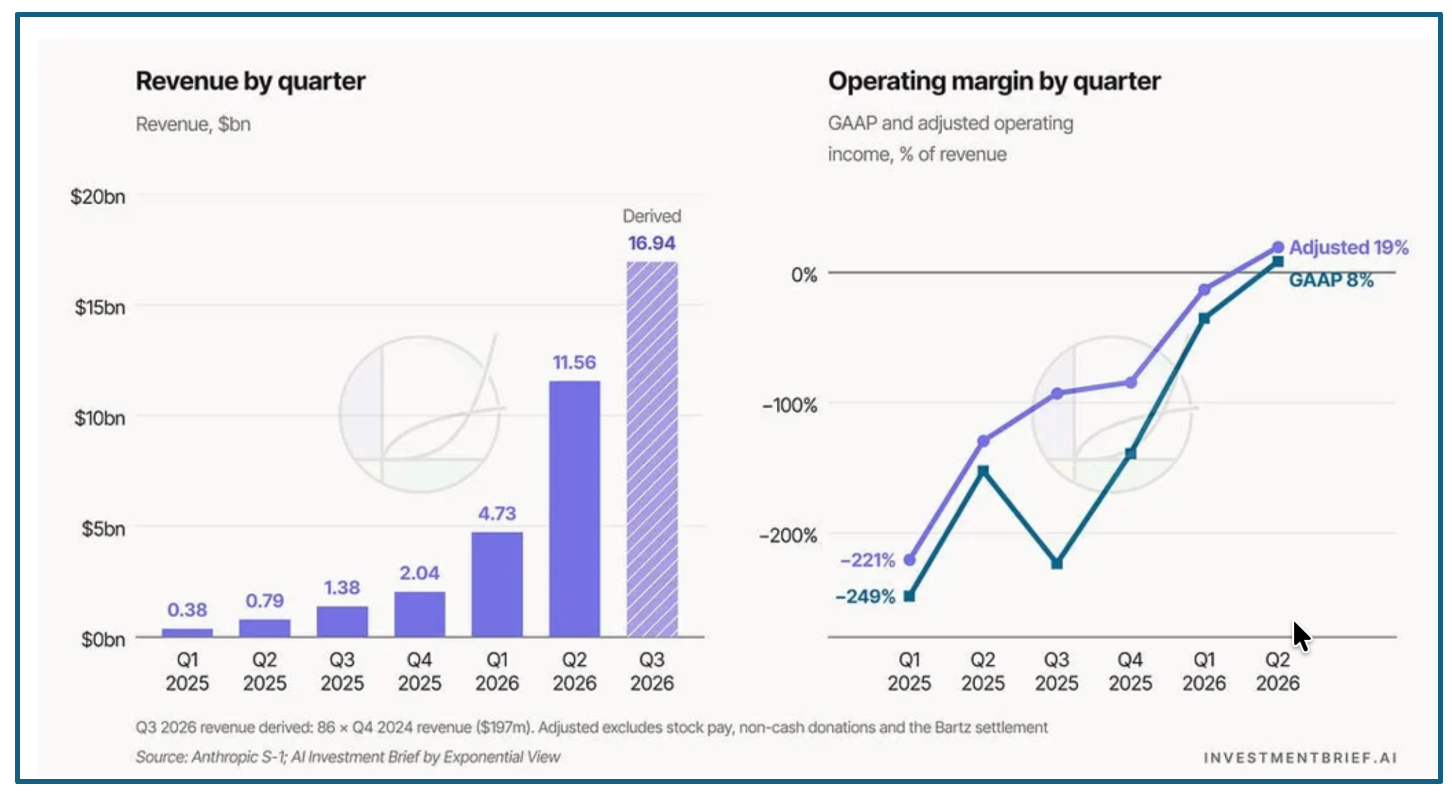
Revenue: $41M in 2023, $386M in 2024, $4.59B in 2025, and $16.3B in the first six months of 2026. Q2 alone was $11.6B.
Rumors are that ANT is going to raise $90-100B. The previous record amount raised in an IPO was SPCX at $75, which expanded to $85.7b with the greenshoe. If ANT gets out successfully (extremely likely), we’ll have a new record IPO. SpaceX is 24yrs old.
Net Revenue Retention of roughly 900%. Not a typo.
Q2 2026 was the first GAAP operating profit: $974M, an 8.4% operating margin. The company is cash flow positive.
Headline net loss for the first half: $80.7B. Hold that thought, we’ll come back to it, because $72.4B of that is non-cash fair-value swings on convertible notes, derivatives and SAFEs (not real operating loss - the anti-AI press has latched onto this number, it’s fake news)
11,900+ customers spending $100K+ a year, up from about 950 a year ago.
No single customer over 10% of revenue; top five are about 25%.
Compute commitments to Broadcom, SpaceXAI, Google, Amazon, Microsoft, Nscale and Lambda that add up to roughly $637B. About $266B of that is fixed or minimum guaranteed as of June 30.
Last private round: $65B Series H at a $965B post-money in May 2026.
Sources for the numbers above: the S-1, Tomasz Tunguz, PitchBook, TechCrunch and CNBC.
My 4 Favorite Charts
Here’s Anthropic’s revenue and margin trends:
This chart indexes Anthropic pre-IPO to public company b2b SaaS companies:
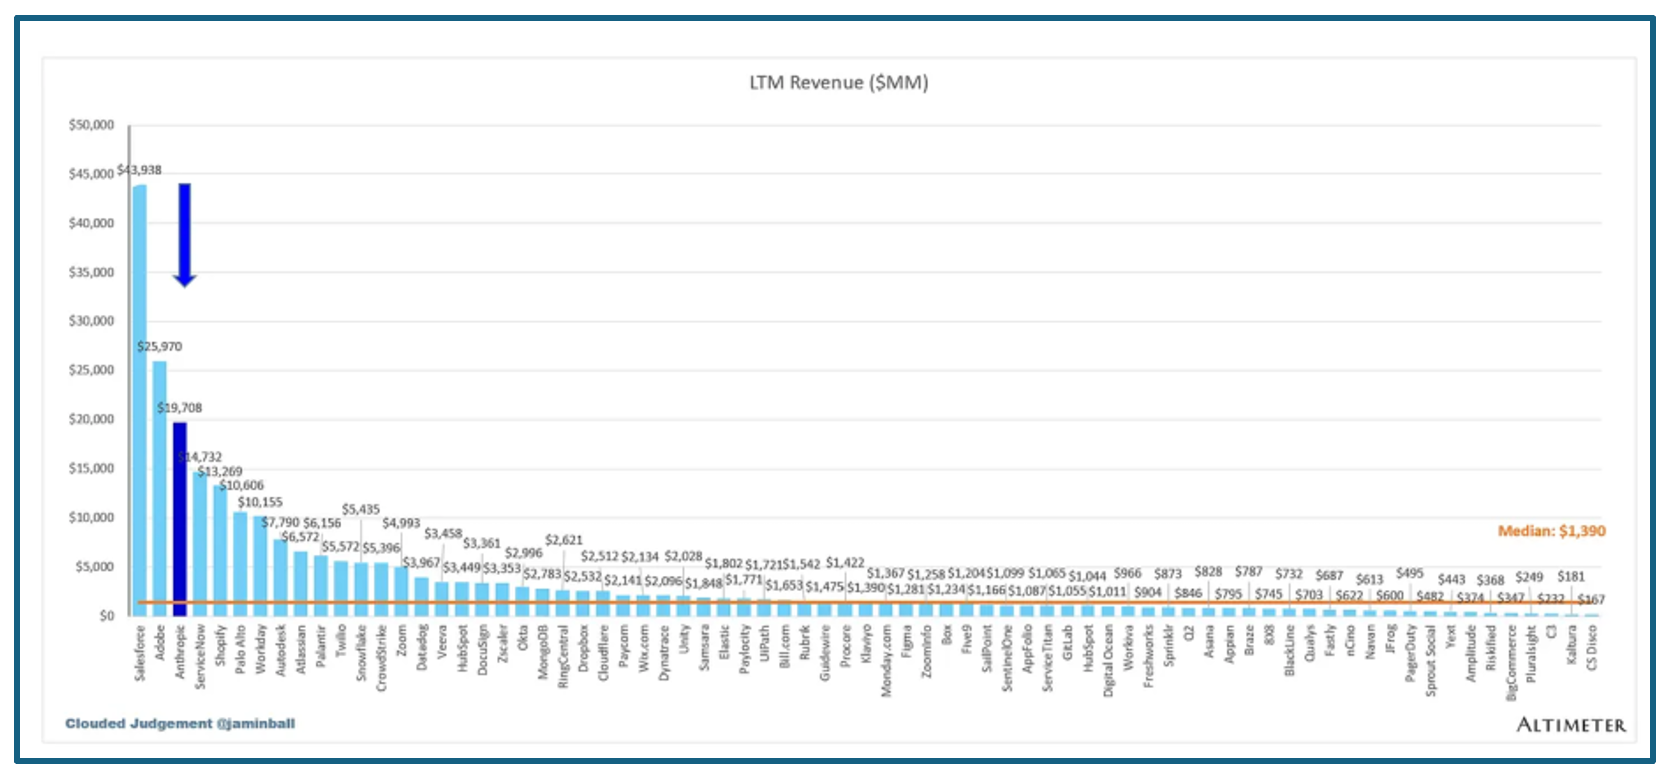
Note they are closing in on Salesforce (27yrs old) and Adobe (43yrs old) - pretty good for a 5-yr old!
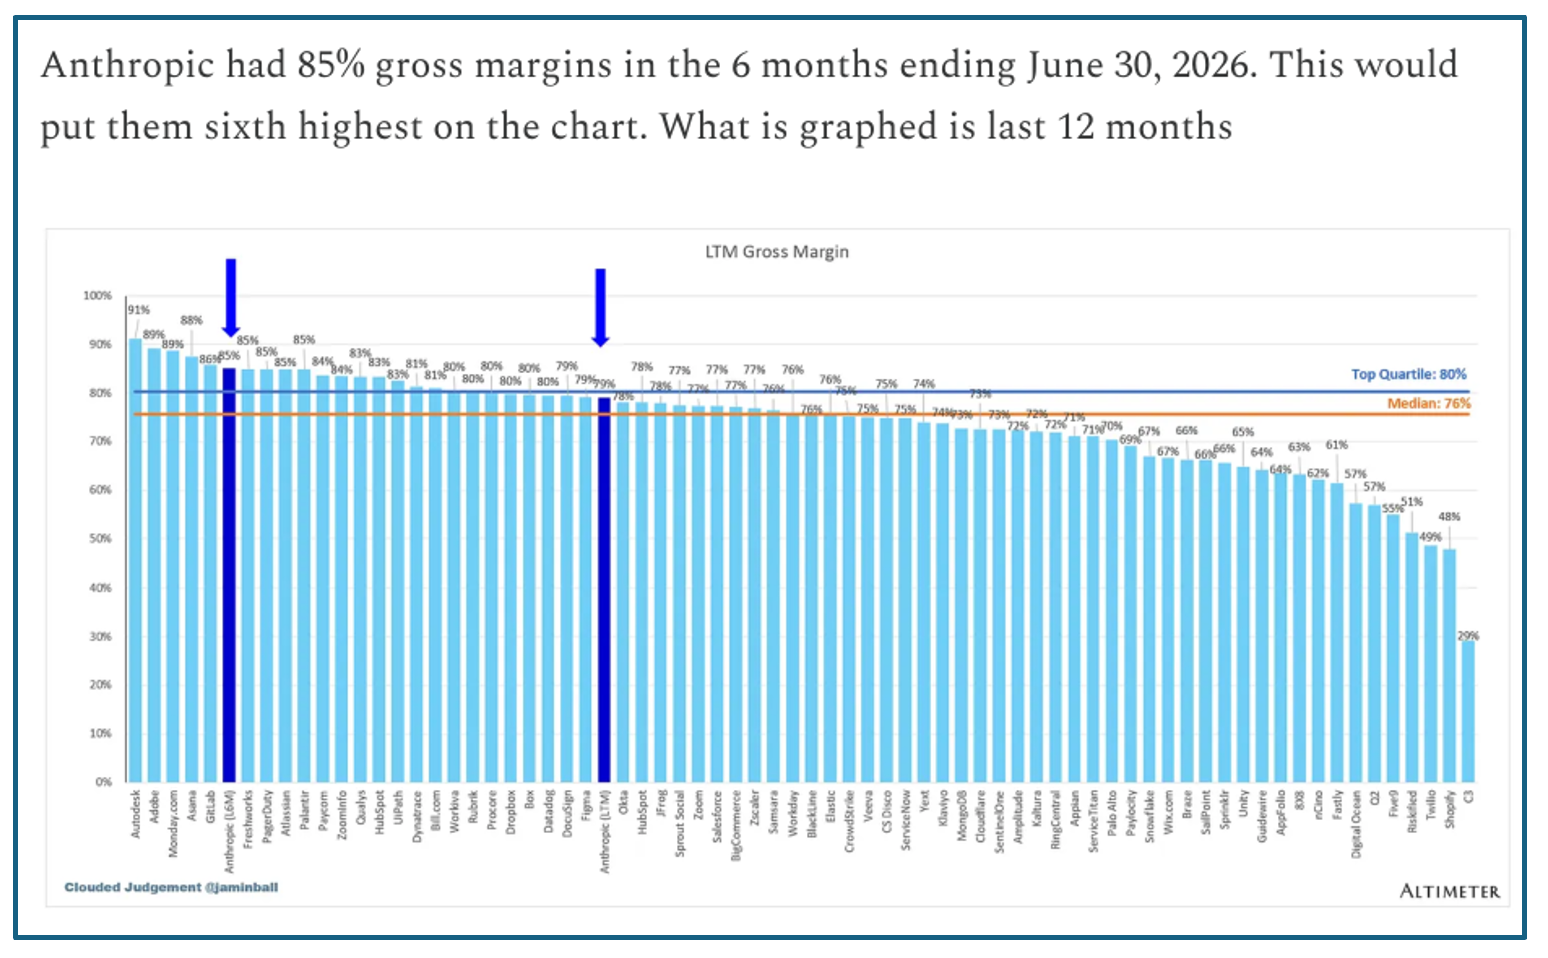
Here’s how their margins stack up - the arrow on the right is trailing 12, but in the last 6 months they have spiked, shooting them up the charts to #6.
My Personal Perspective
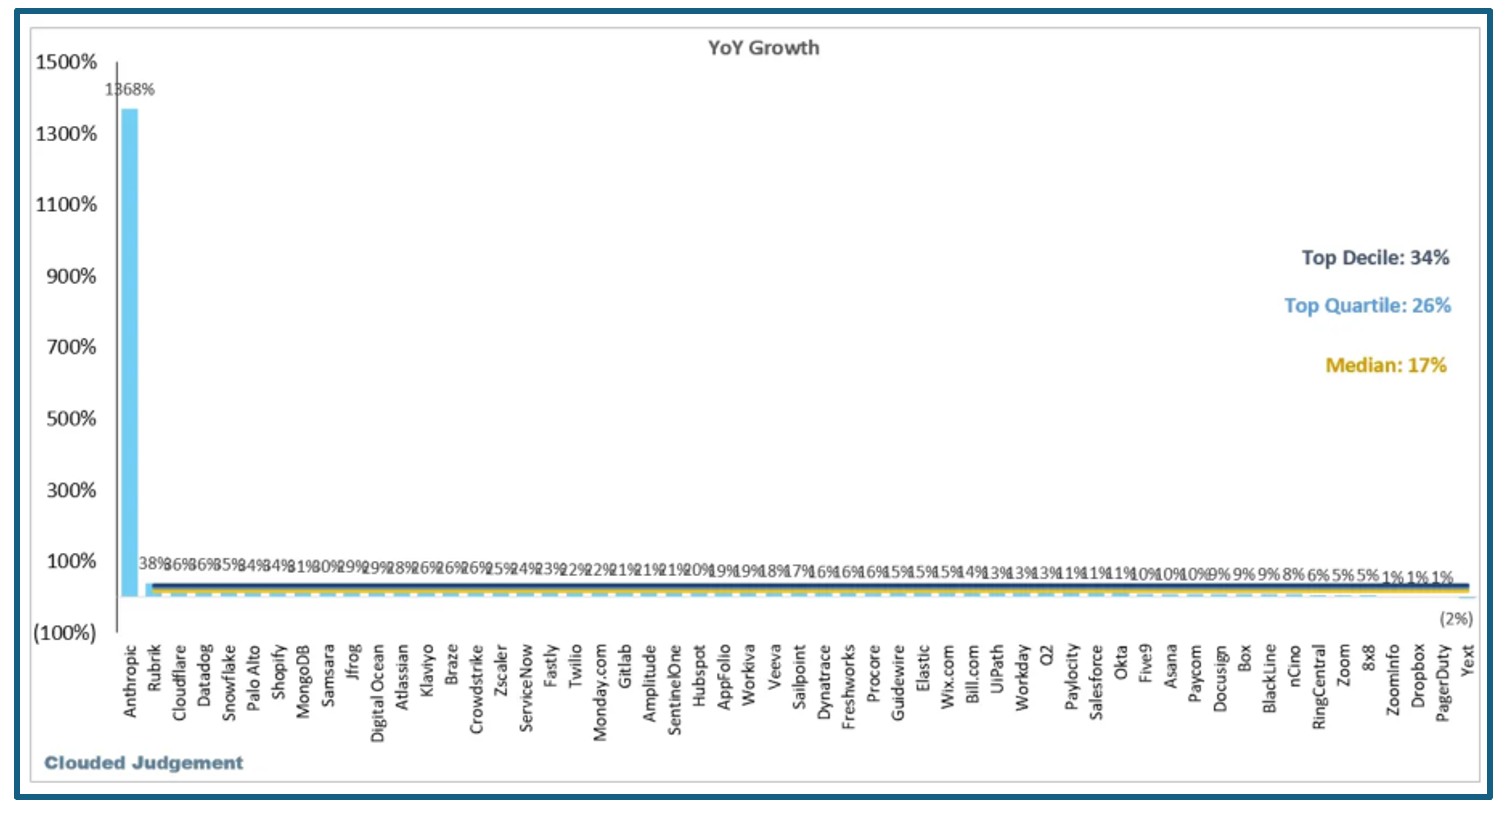
As a ‘working on startup number 5’ multi-time founder who has one IPO under his belt, I can tell from my perspective - reading the Anthropic S-1 is the most humbling and awe-inspiring experience I’ve ever had. I also study other businesses. Amazon is a good business, Google is great, Anthropic is just in another realm - it’s the best business we’ll probably ever see in all our lifetimes. In fact, I saved my favorite chart for here. This one ranks all the public SaaS companies by growth rate. Note how small they have to make the other companies to just fit ANT on there. 🤯
You can find infinite articles gushing over the ANT S-1, so I’ll stop there. What you won’t find is a ‘what it means for me’ - let’s get into that.
Founder Implication 1: ‘Venture Scale’ Just Got Re-priced
Every investor you pitch for the next 18 months will have read this S-1, or at least a summary. Fair or not, that changes the conversation in your fundraising meetings.
For 20 years the venture business ran on a rough rule of thumb: triple, triple, double, double, double. Get to $100M ARR in seven or eight years and you’re a great outcome. Anthropic went from $41M to a $16B in three years. Nobody expects you to do that. But the LP who just got a distribution from an Anthropic fund now has a mental picture of what the upper bound looks like, and your fund manager knows it.
Here’s how I’d translate it for an NC founder raising a seed or an A:
Growth rate is the whole ballgame. This was the conclusion of our Lipson interview and the Airtable post, and the S-1 is the proof. 20% growth got Airtable 2.7x. 1,000%+ growth gets you a $2T IPO. Everything in between is priced along that curve.
Investors now sort you into one of two buckets. Bucket one is businesses where AI is the product and the growth engine. Bucket two is businesses that added an AI tab. The S-1 is the comp for bucket one. Know which bucket you are in before you walk in the room.
Efficiency matters as much as growth. Anthropic’s own language is ‘high talent density’ and ‘scale with a smaller team.’ The 40-people-$40M story we ran with Gradient Health here is the same pattern at NC scale. Revenue per employee is going to show up on more term sheet conversations.
Founder Implication 2: The SaaS Apocalypse Gets a Second Act
If you run a pre-AI SaaS company, this IPO is going to re-rate you one more time. The only question is which direction. The rumor is this is going out Nov 16th, so we’re going to find out soon.
Here’s how I see the three scenarios playing out for a late-stage SaaS founder vs. the AI-company founder:
Scenario 1: ANT Pops
If ANT prices at $2T and prices up from there.
SaaSCo Implications:
What happens in this scenario is capital keeps rotating out of SaaS and into AI - resulting in Airtable-style 2-3x exits become the norm for sub-25% growers.
AICo Implications
Seed and A rounds get even more buzzy and expensive. Every pitch gets the ‘why aren’t you growing 10x’ question.
Scenario 2: ANT Goes Sideways
If ANT prices at more like $1.5T, trades sideways
SaaSCo Implications:
Status quo. Public SaaS stays at 4x. Private marks keep drifting down to meet it.
AICo Implications
Healthy. AI premium holds but discipline returns on burn and margin.
Scenario 3: ANT Broken IPO
In this scenario, ANT has weak demand for the IPO, prices below $1T or trades down hard after the IPO.
SaaSCo Implications:
Ironically the best case for SaaS founders. Money rotates back toward profitable, predictable software. Your 20% growth and 80% gross margin look boring and safe again.
AICo Implications
Reset. Rounds get marked down, bridge rounds everywhere, ‘AI’ comes off the deck.
Notice the SaaS company’s best outcome is the AI company’s worst. That is the trade every founder in NC is sitting on right now.
The Airtable math didn’t get any better this week. If you’re at 20% growth with a 2021 valuation, the window Todd Olson described is closing, and it’s going to be closing in about 20 days. ⏰
Founder Implication 3: If You Build on Claude, Read the Risk Factors Like an API Changelog
This one is personal. ReFiBuy builds against frontier models every day, and a bunch of Tweener portfolio companies do too. The risk factors section reads like a product roadmap with the lawyers’ names on it. Five things I’d flag for any founder with an Anthropic (or OpenAI, or Google) API key in production:
Pricing may move to outcomes. 80% of revenue is consumption. The filing warns that agentic workloads are ‘structurally more compute-intensive’ and that pricing may shift to ‘outcome or task-based’ models. If you run long agent loops, your COGS line could be repriced by someone else’s product team. Model it now.
The platform is coming up the stack. Claude Enterprise users who don’t use Claude Code spend under $75 a month. The top 5% who do spend about 20x that. Cowork (their agent product for non-technical teams) is adopting faster than Claude Code did. And they launched ‘Ode with Anthropic’ with PE firms to go after mid-sized companies directly. If your pitch is ‘Claude plus a UI for industry X,’ re-read our April moats post this weekend, becuase they maybe coming for your industry, especially with a well loaded balance sheet on their side.
Marketplaces are the channel. Nearly half of Anthropic’s revenue flows through AWS and Google Cloud marketplaces. If you sell to enterprise and you aren’t on hyperscaler paper yet, that’s a GTM gap, and Anthropic just showed you the size of it.
No lock-in cuts both ways. Consumption contracts with little or no notice to terminate mean you can switch models fast. They also mean your customers can switch off you just as fast if you’re a thin layer on top. Claude and OpenAI are in a reset and $/token battle right now, this isn’t over by any means and could result in good ole fixed-price SaaS rotating back into the spotlight.
An optimistic read: serving costs are about 15% of revenue and Anthropic keeps cutting price per task. Your model costs keep falling as long as you aren’t the one running the agent loop that never ends.
Founder Implication 4: Cap Table and Governance Lessons (What to Copy, What to Leave Alone)
The cap table story is the part of this S-1 that should give every NC founder who has been told ‘no’ some comfort. Newcomer reports that early backer Anjney Midha pitched Anthropic to 22 venture firms and 21 passed. The Series A was led by Jaan Tallinn, the Skype co-founder, with checks from Dustin Moskovitz and Eric Schmidt. Sand Hill showed up late with all the cash it could wrangle, and the company deliberately kept every firm under 5% so nobody had outsized control. That’s similar to our May post on the elusive lead investor - Investor’s missed this one early. The best companies are often the ones the establishment turns down, and the people who say yes early are rarely the brand-name funds.
Now the parts to leave alone:
SAFE and convertible accounting. That $72B non-cash loss is what happens when instruments you signed at one valuation get marked at a much bigger one. At our scale the lesson is simpler: know your stack of caps and discounts before you sign the next one. A $20M cap SAFE from 2023 sitting under a 2026 priced round at $80M is a 4x mark somebody has to explain to the board.
Strategic money. TechCrunch makes the case that Amazon, which backed a would-be rival early and now sells it most of its compute, is the single biggest financial winner here. The S-1 itself notes that its cloud providers also build competing models. When a strategic writes the check, you are taking on a customer, a supplier and a competitor in one wire. Sometimes that’s exactly right. Go in with your eyes open.
Founder Implication 5: The Liquidity Wave Is Coming to a Seed Round Near You
This is the part I’m most excited about as a seed investor, and it has almost nothing to do with Anthropic’s product.
When a company this size goes public, the money doesn’t sit still. Here’s the chain:
Lockups come off in slices. Reports from The Information say Anthropic is letting some holders sell at the IPO, staggering the lockup beyond 180 days, and putting rank-and-file employees on 10b5-1 plans. PitchBook confirms the standard 180-day crowd gets ‘let out in slices.’ Translation: steady selling pressure through 2027, and steady liquidity for the people holding the shares.
VCs get their DPI event. Spark, Menlo, Iconiq, Lightspeed and friends. None own more than 2%, but at $1.5T a 2% stake is $30B. For most of these firms Anthropic is the largest position in their history.
LPs get distributions, and raise again. Distributions are what have been missing from venture since 2021. When the endowments and pensions get real cash back from the Anthropic funds, those managers go back out and raise. That new money lands in 2027 and 2028 fund vintages, and some of it trickles down to seed.
Employees become angels and founders. Anthropic has a few thousand employees. The PayPal mafia came out of a $1.5B exit. The Google and Facebook waves came out of IPOs 1/20th this size. Do the math on what a few thousand newly liquid, technically elite people do with their time and money.
The open question for NC: does any of this land here? Some of it will. Every NC super LP with exposure through a fund-of-funds or a late-stage co-invest is about to have some funds to invest. And every NC engineer who left for a Bay Area AI lab in 2023 just got a reason to think about coming home with a check.
Worst Practices: Things NOT to Take From This S-1
As is the practice in this series, here are the ways I expect founders to misread this document, based on what’s already coming in on the Tweener Fund help line:
Worst Practice 1: Benchmarking your NRR against 900%. That number is a consumption artifact. A customer who starts with a $5K API pilot and ends up at $50K of monthly tokens shows up as 10x expansion. It says nothing about seat-based SaaS and if you’re an AI native company, paint your own picture of value you are delivering to customers.
Worst Practice 2: Treating consumption pricing as free money. Usage-based revenue is wonderful on the way up. But on the way down, it also has no floor. Anthropic’s own filing calls out that customers can walk with little or no notice. If you move to consumption pricing, model the down case, and keep a committed-spend tier for the customers who want predictability.
Worst Practice 3: Signing infrastructure ahead of revenue because ‘Anthropic does it.’ Anthropic contracts compute 12 to 18 months ahead with $130B in the bank and a product that triples every quarter. You have 14 months of runway and a product that grew 40% last year. Those are not the same bet. Buy capacity when customers are paying for it.
Worst Practice 4: Building a thin layer and calling it a company. The Claude Code 20x spend number, Cowork, and Ode with Anthropic are three data points that say the same thing: the model company is moving into the workflow. If your entire value is a prompt and a nice UI, the S-1 just told you how long you have.
Conclusion
The singular action every founder can take from this S-1 is the same one I pulled out of the Airtable deal in August, just with more conviction: decide which company you are. Either you are an AI-native growth story and you price your raise, your hiring and your burn against the curve this S-1 just drew, or you are a pre-AI company making its AI bet, and you say so plainly and run the Lipson playbook with everything you’ve got. The founders who get hurt will be the ones in the middle, with an AI tab on the product and a SaaS multiple in their heads.
Where does your company sit on the ANT spectrum? What does your 2027 plan look like if ANT prices at $2T, and what does it look like if it breaks $1T?
Hit reply and let me know. If there’s enough interest, I’ll do a follow-up with some core NC founder responses once the stock starts trading.
Enjoying the content? Don’t forget to →